A Crédit Agricole mortgage can include renovation work, provided it is related to improving or transforming the property. This option affects how the project is financed: the loan term, applicable interest rate, how funds are released and which expenses are eligible all vary depending on whether the work is included in the mortgage or financed separately with a consumer loan.
The 10% threshold: the HCSF requirement for including renovation work
The French High Council for Financial Stability (HCSF) allows banks to include renovation work in a mortgage when the work accounts for at least 10% of the total cost of the transaction. This threshold applies to purchases of older properties that require renovation.
In practice, the property price and the cost of the work are added together to calculate the total project cost. The renovation work must account for at least this minimum share for the bank to treat the entire amount as a mortgage. Below this threshold, the work must be financed with a consumer loan, which comes with different terms, including a shorter repayment period and often a higher interest rate.
This is not an automatic entitlement. Crédit Agricole, like any bank, applies its own lending criteria, including the debt-to-income ratio, disposable income and the strength of the application. Meeting the HCSF threshold makes it possible to include the work, but does not guarantee approval. The list of renovation work eligible for a Crédit Agricole loan also depends on the type of work planned for the property.
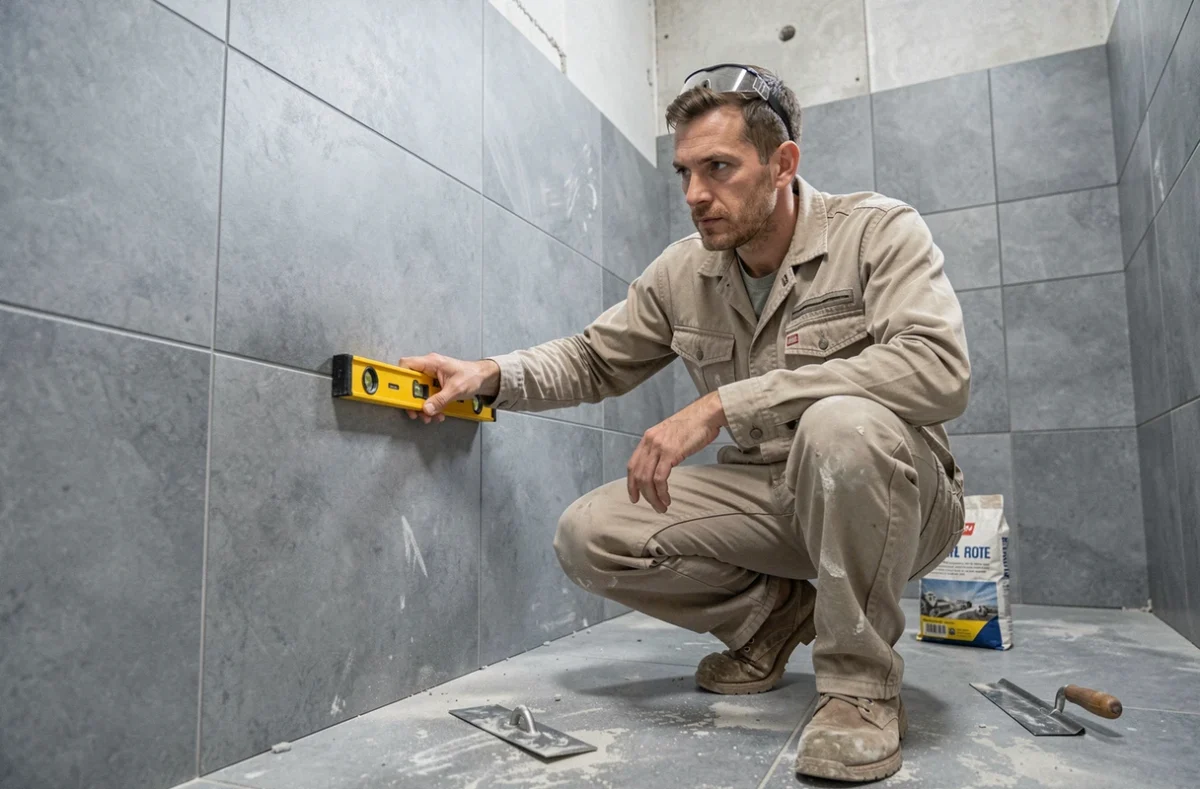
Renovation work eligible for a Crédit Agricole mortgage: accepted categories
Not all projects are viewed equally by the bank. The key criterion is that the work must improve, transform or restore the property. Expenses that are purely decorative or relate to routine maintenance (repainting a wall or replacing a tap, for example) generally do not qualify for mortgage financing.
Renovation work typically accepted as part of a Crédit Agricole mortgage covers a broad range of projects, provided they are supported by quotes:
- Energy-efficiency upgrades: thermal insulation (walls, attics and floors), window replacement, installation of an efficient heating system, mechanical ventilation
- Structural and major building work: roof repairs, alterations to load-bearing walls, construction of an extension or an additional storey
- Upgrades to meet technical standards: complete rewiring, plumbing upgrades to meet current standards, connection to the public sewer system
- Major interior renovations: a complete kitchen or bathroom remodel (rather than simply replacing a cabinet or fixture)
Crédit Agricole requires invoices before releasing the funds. The money is released in stages, as the work progresses, rather than as a single payment when the loan is signed.
Mortgage or consumer loan for renovation work: how the terms differ
The distinction between these two types of financing affects three key factors.
Repayment term and maximum loan amount
A consumer loan for renovation work is capped at €75,000 and must be repaid within 15 years. Above this amount, the financing falls into the mortgage category, with repayment terms of 15 to 20 years or even longer, depending on the borrower’s profile.
For major renovations (roof repairs, full insulation or structural alterations), the €75,000 cap is often insufficient. Including the work in the mortgage makes it possible to spread repayments over a longer period, reducing the monthly payment.
Interest rates and monthly payment smoothing
Mortgage interest rates are generally lower than those on consumer loans. Monthly payment smoothing allows the cost of the work to be incorporated into the overall loan payment, avoiding the burden of two separate repayments while the work is underway.
A borrower who takes out a standard mortgage and a separate renovation loan has to make two distinct monthly payments. Financing the project as a whole avoids this situation.
MaPrimeRénov and éco-PTZ: how they work alongside a mortgage
Public grants for energy-efficiency renovations can supplement a mortgage, but the scope of these schemes has changed recently. Homeowners wishing to benefit from MaPrimeRénov often need to commit to a comprehensive renovation plan rather than carrying out isolated improvements.
The zero-interest eco-loan (éco-PTZ) can still be used to finance energy-efficiency renovations. It can provide up to €50,000 for a comprehensive renovation, with no application fees and no interest. It can be combined with the main mortgage.
One important point that is often overlooked: the type of heating system retained after the work may affect eligibility for grants. Checking this before finalising quotes can help avoid finding out too late that part of the planned financing will not be covered.
Work without quotes or carried out by the borrower: what the bank accepts
Crédit Agricole finances renovation work based on quotes from professionals. Work carried out by the borrower (partial self-build) can be difficult to document: without a contractor’s invoice, funds cannot be released in stages under the standard process.
Some Crédit Agricole regional branches may allow a portion of the work to be carried out by the borrower as part of the financing plan, but this is at the discretion of the adviser and depends on local policy. The basic rule is that every euro released for renovation work must be supported by an invoice.
For energy-efficiency renovations that qualify for grants, the work must be carried out by an RGE-certified contractor (Recognised Environmental Guarantor).
Arranging a Crédit Agricole mortgage that includes renovation work therefore comes down to three requirements: the work must be eligible, it must be supported by detailed quotes from professionals, and the HCSF threshold must be met when buying an older property. Checking all three before meeting with the bank can help speed up the application process.